QSBS: The Startup Tax Strategy Worth Millions
Resources from Michelle Stricklin, CPA’s Reno Startup Week presentation
Section 1202 Qualified Small Business Stock, or QSBS, can potentially allow eligible founders and investors to exclude millions of dollars of gain from federal income tax.
But QSBS planning doesn’t start when you’re ready to sell.
It starts when you form, fund and grow the company.
*By submitting this form, you agree to receive marketing communications from Meliora Consulting, PLLC, including but not limited to this resource, via email. You can unsubscribe at any time using the link in our emails. For more information, please review our Privacy Policy.
Could Your Stock Qualify for QSBS?
QSBS can be incredibly valuable, but eligibility depends on a series of requirements involving the company, the shareholder, how the stock was acquired, what the business does, and what happens during the holding period.
For qualifying stock acquired after July 4, 2025:
50%
exclusion after
3 years
75%
exclusion after
4 years
100%
exclusion after
5+ years
IMPORTANT CONTEXT
A Note About the New Threshold
The 2025 legislation also increased the gross-assets threshold for newly issued qualifying stock from $50 million to $75 million, with inflation adjustments beginning in 2027.
Different rules can apply to stock acquired on or before July 4, 2025.
The decisions you make today can determine whether a future exit qualifies for a significant tax benefit.
The Founder’s QSBS Checklist
12 questions worth asking before your company becomes significantly more valuable
Use this checklist to identify potential QSBS opportunities and issues to discuss with your tax and legal advisors.
Keep Learning
What Is QSBS? A Founder’s Guide to Section 1202
Understand the basic requirements, potential exclusion and why founders should evaluate QSBS long before an exit.
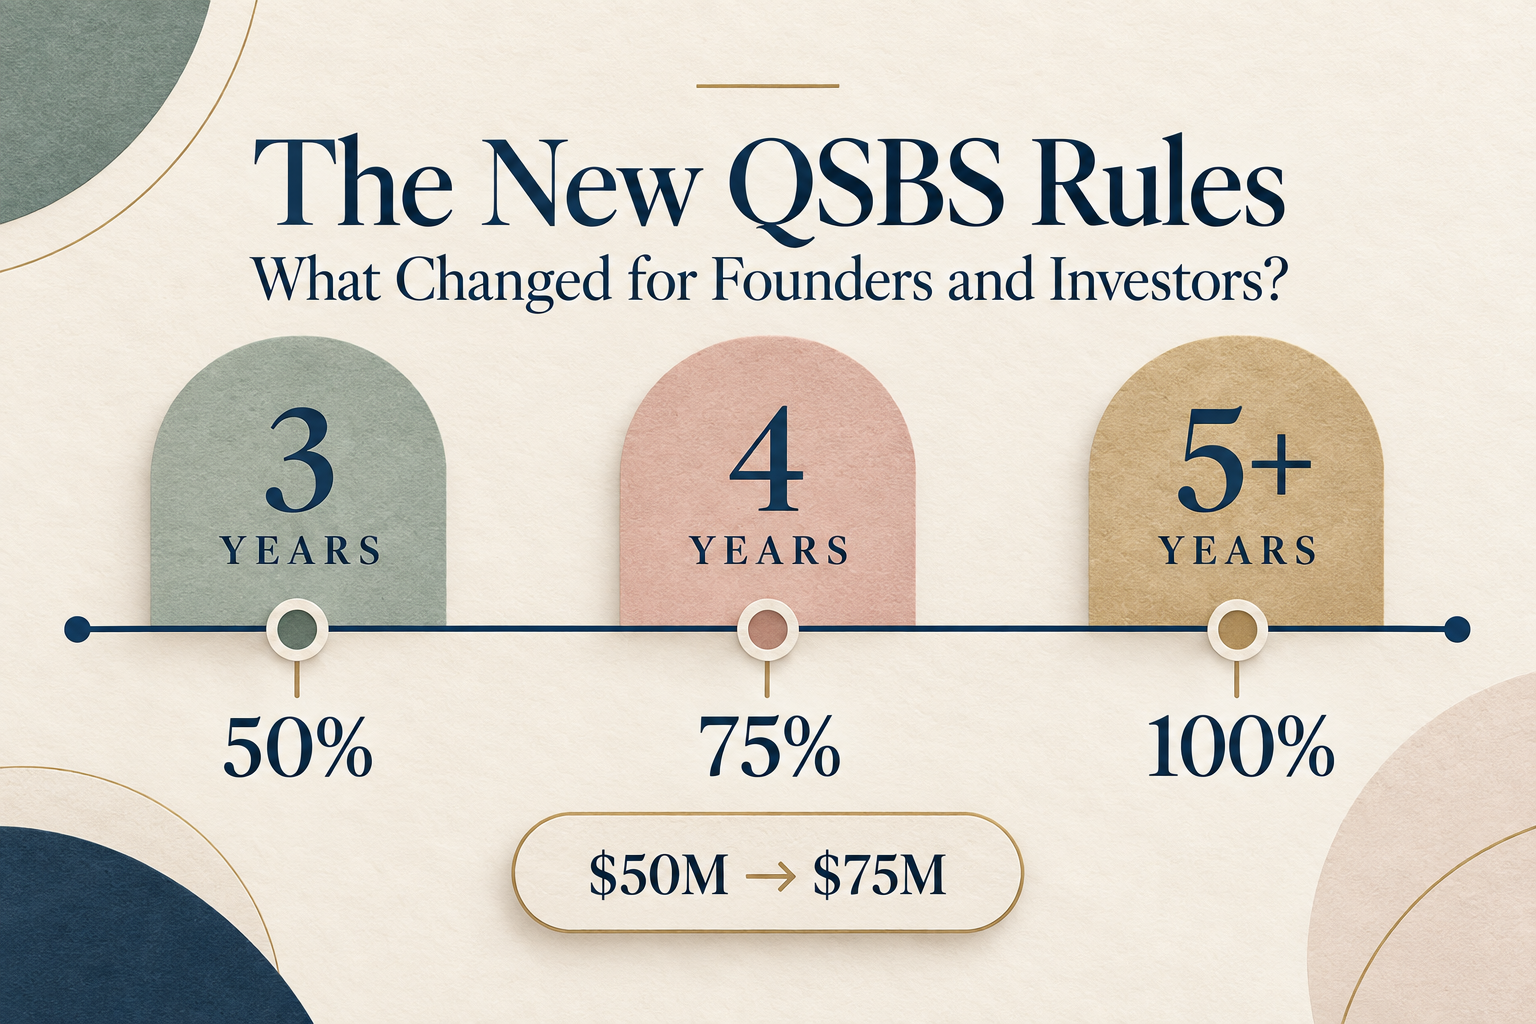
The New QSBS Rules: What Changed for Founders and Investors?
Learn how the 2025 tax legislation changed holding periods, exclusion percentages and the gross-assets threshold for newly issued stock.
LLC, S Corp or C Corp: Why Entity Choice Matters
Taxes shouldn’t be the only consideration when selecting an entity, but the potential availability of QSBS can make the C corporation conversation significantly more important.
Tax Decisions Compound as Companies Grow
QSBS planning does not begin when a company is ready to sell. Entity choice, how stock is issued, fundraising decisions and changes in the business can all affect whether the exclusion may be available later.
These decisions are often made years before an exit is even being considered.
The decisions you make today can determine whether a future exit qualifies for a significant tax benefit.
BEYOND QSBS
Tax Leadership Before You Need a Tax Department
The same is true of many issues growing companies encounter:
Entity structure • Equity compensation • R&D • State expansion • M&A • International growth • Tax provision • Tax compliance
Companies often reach a point where tax has become too complicated to simply hand off once a year, but they aren’t ready to hire a full-time tax executive.
That’s where Meliora Consulting comes in.
Meliora provides growing companies with fractional tax leadership, tax infrastructure and proactive advisory to help make sure someone is looking around the corner.
ABOUT
Meet Michelle Stricklin, CPA
Michelle brings extensive corporate and public-company tax experience to growing businesses through Meliora Consulting.
Her work focuses on helping business owners and finance leaders understand tax decisions before they become tax problems, coordinating the moving pieces of the tax function and building the infrastructure companies need as they grow.
Presented at Reno Startup Week 2026
QSBS: The Startup Tax Strategy Worth Millions
Have a QSBS Question?
QSBS is highly fact-specific. If you’re forming a company, issuing stock, raising capital, restructuring ownership or preparing for a potential transaction, it’s worth evaluating the rules before making decisions that may affect eligibility.
Information provided by Meliora Consulting is for general educational purposes and should not be considered tax or legal advice. QSBS eligibility depends on the specific facts and circumstances of the corporation and shareholder.
© 2025 Meliora Consulting